Table of Contents
Last Updated: October 20, 2026
Can You Settle a Personal Injury Claim Without Legal Representation?
Yes, you can achieve personal injury settlements without lawyer representation. Many people negotiate directly with insurers and reach fair settlements on their own, provided they prepare carefully, document clearly and understand their claim's value. (Source: The Scottish Parliament's legislation)
Insurers want evidence that proves liability and quantifies your losses. Provide it and negotiations become straightforward; without it, insurers will lowball your offer.
This guide covers the process and the pitfalls.
Whether your injury arose from a road traffic accident, a workplace incident or a slip and trip, the fundamentals are the same: document everything, calculate your damages accurately and communicate your position clearly.
Pro Tip
Start gathering evidence immediately after your accident. Memories fade, witnesses move away, and photographs lose detail over time. The sooner you act, the stronger your position.
Personal Injury Claim Evidence Checklist
Your evidence determines whether an insurer takes you seriously. Without it, they'll dismiss your claim or offer minimal compensation.
Documenting the accident scene
Photograph everything at the scene while it's fresh: wide shots of the location and close-ups of the hazard, damage or conditions that caused the injury. If you slipped, photograph the wet floor or broken surface; if hit by a vehicle, photograph both vehicles and the road conditions.
Note the date, time and weather, plus witnesses' names and contact details. Even brief statements are valuable, insurers trust eyewitness accounts far more than your account alone.
Request an incident report from the property owner, employer, or business where the accident occurred. These reports often contain details you'll forget and strengthen your claim.
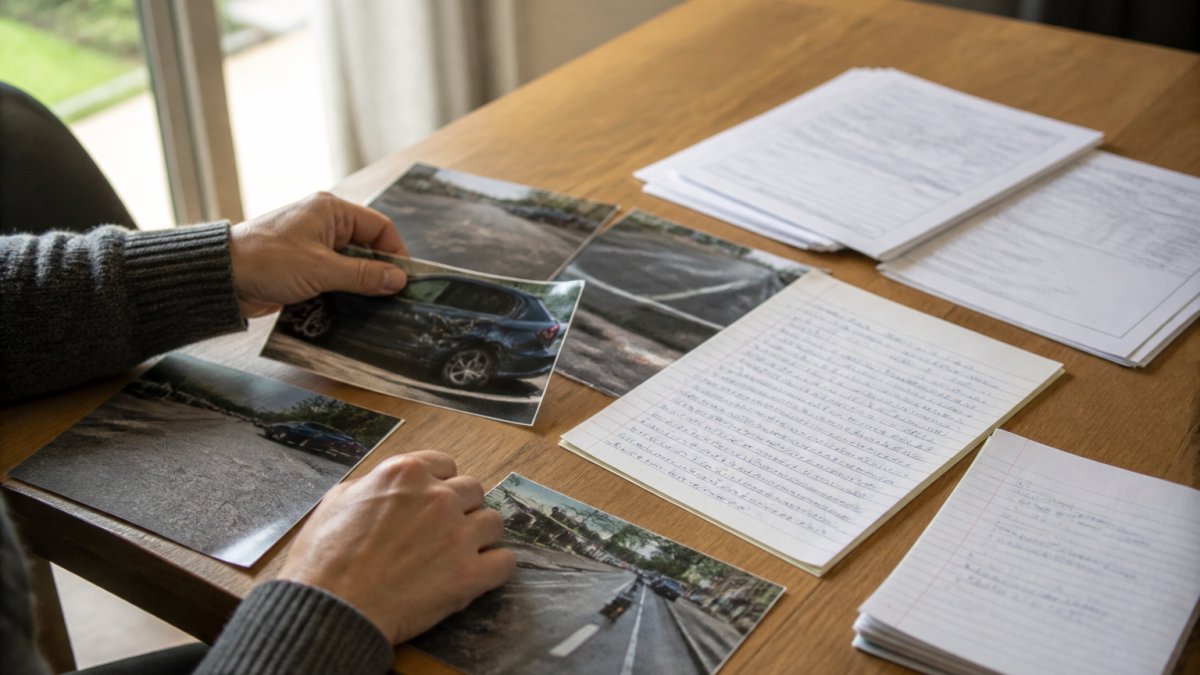 Person's hands arranging accident scene photographs, medical records, and handwritten witness statements on a table in natural window lighting
Collecting medical evidence
Seek medical treatment immediately, even for minor injuries. Medical records are your strongest proof that an injury occurred and its severity.
Request copies of all treatment records from:
- Your GP
- Hospital A&E departments
- Physiotherapists or specialists
- Any private practitioners you consulted
Keep receipts for prescriptions, medical equipment, travel to appointments and any private treatment, as these prove your out-of-pocket costs.
Photograph visible injuries, bruises, cuts or swelling, on the day of the accident and at regular intervals during recovery. These images are compelling evidence of severity.
Keep a recovery diary noting pain levels, mobility restrictions, time off work and impact on daily activities. It supports your claim for pain and suffering damages.
| Evidence Type |
Purpose |
Collection Timing |
| Accident scene photos |
Proves hazard or fault |
Immediately after accident |
| Medical records |
Proves injury and treatment |
Within 2 weeks of treatment |
| Medical bills |
Quantifies treatment costs |
As you receive them |
| Witness statements |
Corroborates your account |
Within days of accident |
| Incident report |
Documents official record |
Within 1 week |
| Recovery diary |
Demonstrates ongoing impact |
Throughout recovery period |
Assessing Your Claim Value and Damages
Understanding what your claim is worth prevents you from accepting lowball offers. Insurers count on claimants undervaluing their own injuries. In Scotland, valuation follows Scots law and Scottish practice, not pain-and-suffering formulas imported from elsewhere.
Damages in Scotland fall into two categories: patrimonial loss (financial losses) and solatium (general damages for pain, suffering and loss of amenity). Using the correct terminology when writing to a Scottish insurer or raising a court action signals you understand the process.
Patrimonial loss covers quantifiable financial losses caused by the accident. Itemise each head precisely:
- Earnings lost to date, calculated from your actual net pay (payslips, P60, or a letter from your employer)
- Future loss of earnings where recovery is incomplete or a return to your previous role is uncertain
- Treatment costs not available on the NHS, such as private physiotherapy or dental work
- Prescription charges and over-the-counter medication
- Travel to and from appointments, including mileage at a reasonable rate per mile
- Care provided by family or friends, and paid care where needed
- Adaptations to your home, such as grab rails or a temporary downstairs bedroom
- Replacement services, for example gardening or cleaning you can no longer do
Keep every receipt, bank statement and payslip. A simple spreadsheet with date, description, amount in pounds and document reference is enough, insurers respond well to a clean schedule and discount vague round-sum claims.
Solatium compensates for pain, suffering and loss of amenity. Scottish courts assess it by reference to injury severity, recovery duration, permanent disability and impact on daily life. There is no statutory tariff; practitioners look to:
- The Judicial College Guidelines (published for England and Wales but widely used as a cross-check in Scotland)
- Reported Scottish decisions in the Court of Session and the Sheriff Appeal Court, available via the Scottish Courts and Tribunals Service website (Judgments)
- The Judicial Institute for Scotland's sentencing and damages materials where relevant
Bracket your injury: a soft-tissue whiplash injury resolving within months attracts modest solatium; a fracture requiring surgery and physiotherapy with residual stiffness rises substantially; a serious spinal or brain injury with lifelong consequences can run into six figures and will almost certainly need specialist representation.
Worked example, a straightforward road traffic claim in Glasgow
Suppose you were rear-ended on the M8 near Glasgow, suffered a whiplash injury and a fractured wrist, were off work for six weeks, and attended private physiotherapy. A defensible schedule might look like this:
| Head of claim |
Basis |
Amount |
| Lost net earnings |
6 weeks at your net weekly pay |
£[your figure] |
| Private physiotherapy |
8 sessions at the invoiced rate |
£[your figure] |
| Prescriptions |
Receipted |
£[your figure] |
| Travel to appointments |
Mileage at a reasonable rate |
£[your figure] |
| Solatium |
Bracketed by comparable Scottish decisions |
£[your figure] |
| Total |
|
£[your figure] |
Insert your own documented amounts rather than copying figures from another claim. The table shows the insurer that every pound is evidenced and your solatium figure is reasoned.
Deductions to consider before you accept
- Benefits recoupment. If you received certain state benefits linked to the injury, the Compensation Recovery Unit may recover them from the insurer (Recovery of benefits and lump sum payments and NHS charges: technical guidance). This is deducted from the settlement, not added to it.
- Credit hire or rehabilitation. If your insurer or a credit hire company paid for a replacement vehicle or rehabilitation, those sums may be recoverable from your settlement.
- Your own legal costs. If you later instruct a solicitor, check the fee arrangement carefully. Many Scottish personal injury solicitors work on a no-win, no-fee basis, but success fees and insurance premiums can reduce your net award.
Watch Out
Avoid inflating your claim with exaggerated injuries or invented losses. Scottish insurers investigate thoroughly; dishonesty destroys your credibility and can expose you to a finding of fraud and an adverse award of expenses in court.
Build your valuation from the bottom up: every receipt, every payslip, every appointment. Then bracket your solatium against comparable Scottish decisions. A reasoned schedule in pounds is far more persuasive than a single round-number demand.
If your symptoms are ongoing, ask your GP or consultant for a report setting out diagnosis, treatment to date, prognosis and any permanent impairment. A clear medical opinion is the single strongest lever in Scottish settlement negotiations.
Writing a Personal Injury Settlement Negotiation Letter Template
Your demand letter is your formal opening position: professional, evidence-backed and clearly reasoned. Insurers take written demands more seriously than casual conversations.
Structure and key components
Start with your contact details and the date. Address the letter to the claims handler or the insurer's legal department, use the name from your policy documents or claim correspondence.
Open with a clear statement of your claim. Identify the accident date, location, and how it occurred. State that you're seeking compensation for injuries sustained due to the insurer's policyholder's negligence.
Describe the accident in detail. Explain how the other party was at fault. Reference weather conditions, visibility, or hazard details that support your account. This section proves liability, the foundation of your claim.
Document your injuries and treatment, listing every appointment, procedure and treatment with dates and costs, and explain how the injury affected your work, daily activities and quality of life.
Calculate your damages. Break special damages into clear line items: medical costs, prescriptions, travel expenses, lost wages. Show your arithmetic. For general damages, reference comparable cases or explain your reasoning based on injury severity and duration.
State your settlement demand. Be specific: "I seek compensation of £[amount] in full and final settlement of this claim."
Close professionally. Request a response within 14 days. Provide your contact details.
What to include and what to avoid
Reference your medical records, receipts, witness statements and photographs, and attach copies of key documents.
Avoid emotional language or anger, insurers respond to facts, not frustration.
Don't make threats or ultimatums unless you're genuinely prepared to pursue legal action. Hollow threats weaken your position.
Avoid admitting fault for any aspect of the accident. Stick to facts that demonstrate the other party's negligence.
Don't inflate your claim with invented costs or exaggerated injuries. Stick to documented, genuine losses.
Your demand letter is a negotiating document, not your final position. Set it higher than your minimum acceptable settlement, but within a defensible range based on comparable cases.
Notifying the Insurer and Starting Your Claim
In Scotland, notifying the insurer is one step in a process governed by Scots law and Scottish court rules. Getting the sequence right protects your position and can shorten negotiations.
Limitation, the clock that matters most
Under the Prescription and Limitation (Scotland) Act 1973, the general limitation period for a personal injury claim is five years from the date of the accident, or from the date you first knew (or ought reasonably to have known) that you had an injury and that it was attributable to the defender's act or omission. That is longer than the three-year period in England and Wales, but it is not a reason to delay. Evidence deteriorates, witnesses move, and insurers harden their positions over time. Note also that limitation can be shorter in some special cases, and that a child's period generally does not start running until their sixteenth birthday. If you are close to the five-year mark, take advice immediately, a court action must be raised before the period expires.
Get Started Today →
The Personal Injury Pre-Action Protocol (Scotland)
Before a court action is raised, parties are expected to follow the Personal Injury Pre-Action Protocol. In practice this means:
- Letter of claim. You send the defender or their insurer a written claim setting out the facts, the injuries, the heads of loss and a broad indication of value. The protocol expects this to be done promptly.
- Acknowledgement. The insurer should acknowledge the letter of claim within a set period and identify the relevant claims handler.
- Investigation and response. The insurer investigates liability and causation and should respond with its position, including any admissions or disputes.
- Disclosure. Both sides exchange relevant documents, medical records, wage evidence, accident reports and photographs.
- Consideration of settlement. Parties should genuinely consider settlement before litigating.
Following the protocol demonstrates good faith. Ignoring it can lead to cost penalties if the claim later goes to court, and it gives the insurer an easy reason to stall.
Which court?
If negotiations fail, you need to know where a claim would be raised:
- All-Scotland Sheriff Personal Injury Court. Based in Edinburgh but with national jurisdiction, this court handles personal injury claims above the sheriff court's ordinary financial limit. It is the default forum for most mid-value Scottish personal injury actions.
- Sheriff Court (local). Suitable for lower-value claims within the relevant sheriffdom.
- Court of Session (Edinburgh). The supreme civil court in Scotland, used for higher-value or complex claims. It is more expensive and slower, and insurers know it.
Understanding the likely forum helps you gauge the insurer's appetite to settle. An insurer facing a Court of Session action with a strong medical report is more likely to move.
Practical notification steps
- Contact the insurer's claims department in writing. Provide the policy or claim reference, the accident date and location, and a brief description of what happened.
- Ask for the claims handler's name, direct line and email. Record every contact.
- Request the claim form and complete it thoroughly and honestly. Incomplete forms delay processing.
- Send the completed form and supporting documents by recorded delivery or by email with a read receipt. Keep copies of everything.
- Follow up within a week to confirm receipt, and agree a communication schedule, weekly or fortnightly updates keep momentum.
- Respond promptly to requests for further information, medical evidence or photographs.
Watch Out
Do not discuss liability, admit fault, or give a recorded statement to the insurer before you have taken advice. In Scotland, as elsewhere in the UK, early admissions can be used against you. Stick to the facts of what happened and let the evidence speak.
Keep a single chronological file, letters, emails, receipts, medical appointments and phone notes. If the claim later needs a solicitor or a court action, a well-ordered file saves time and money.
How to Respond to a Low Personal Injury Settlement Offer
Insurers almost always open with an offer below fair value. This is standard practice. Your response determines whether you'll reach a reasonable settlement or need to escalate.
Evaluating the initial offer
Don't reject an offer immediately out of emotion. Analyse it objectively against your calculations and comparable cases.
Does the offer account for all your special damages? Check whether they've included every medical cost, prescription, travel expense, and lost wage.
Does the general damages component reflect injury severity and duration? Compare it to comparable cases. If it's substantially lower, you have grounds to counter.
Request a breakdown of how the insurer calculated the offer. Understanding their reasoning helps you identify gaps in their assessment.
Submitting a counteroffer with supporting evidence
Respond in writing. Reference the insurer's offer and explain why it's insufficient.
Highlight any special damages they missed. Provide receipts or documentation for items they didn't include.
Explain why general damages should be higher. Reference comparable cases or court judgments. Describe the ongoing impact of your injury.
Submit new evidence if you have it. Additional medical reports, updated treatment records, or new witness statements strengthen your position.
Make a specific counteroffer. Bridge the gap between their offer and your demand, but don't drop too far. This signals you're negotiating in good faith whilst maintaining a defensible position.
Set a deadline for response, typically 14 days. This creates urgency without being aggressive.
Expect the insurer to counter your counteroffer. Most claims settle through several rounds of back-and-forth negotiation. Each round typically moves closer to a middle ground.
When to Accept a Personal Injury Settlement Offer
Knowing when to accept prevents you from rejecting fair offers or accepting inadequate ones.
Accept when the offer fairly reflects your documented losses and is consistent with comparable cases. If you've received medical evidence of full recovery, accepting sooner makes sense. If you have ongoing symptoms, hold out for compensation that covers future treatment.
Reject if the offer clearly undervalues your claim. If comparable cases support a substantially higher settlement, you have grounds to continue negotiating.
Consider your circumstances. If you need money urgently, a slightly lower offer may be acceptable. If you can wait, holding out for more often succeeds.
Accept when further negotiation seems unlikely to improve the offer. Some claims reach a point where both parties have stated their final positions. Continuing to push rarely yields results.
Once you accept, you'll sign a settlement agreement and release of claims. This document confirms you accept the settlement in full and final settlement of the claim. You cannot pursue further compensation after signing.
Self-negotiated settlements work best for straightforward claims with clear liability and documented injuries. Complex claims, serious injuries, or disputed liability benefit from professional representation.
Common Mistakes to Avoid When Negotiating Without Legal Help
Claimants often undermine their own positions through preventable errors.
Starting negotiations before gathering evidence. Many people contact the insurer immediately after an accident, before they've documented the scene or collected witness statements. Insurers lock in low offers early, knowing you'll struggle to improve them without evidence. Gather everything first, then open negotiations.
Accepting the first offer. The insurer's opening position is deliberately low. Accepting it immediately leaves money on the table. Counter every offer below your realistic valuation.
Failing to document special damages thoroughly. Claimants often forget to claim for prescriptions, travel costs, or lost wages because they didn't track them systematically. Create a spreadsheet as expenses occur. Include every legitimate cost.
Overestimating general damages without justification. Demanding compensation far above comparable cases weakens your credibility. Research realistic ranges and stay within them.
Communicating by phone. Verbal conversations leave no record. Insurers deny statements you made and claim you agreed to things you didn't. Always communicate in writing, email or letter. This creates an audit trail.
Admitting fault. Saying "I should have been more careful" or "I wasn't paying attention" can be used against you. Stick to facts. Let the evidence speak.
Missing deadlines. Insurers set response deadlines. Missing them can result in claim rejection. Mark all deadlines in your calendar and respond before they expire.
Discussing the claim on social media. Insurers monitor social media. Posts about your recovery, activities, or settlement can be used to argue your injuries weren't as serious as claimed. Keep your claim private.
Failing to follow the pre-action protocol. In Scotland, the Personal Injury Pre-Action Protocol sets out the steps both parties should follow before court proceedings. Following this protocol demonstrates good faith and often resolves claims faster. Ignoring it can result in cost penalties if the claim reaches court.
Negotiating personal injury settlements without lawyer involvement is achievable when you're organised, thorough, and realistic about your claim's value. The process rewards preparation. Gather evidence immediately, calculate your damages accurately, and communicate clearly with the insurer.
If your claim becomes complex, disputed, or the insurer refuses to negotiate fairly, professional representation becomes valuable. Scotland Claims Injury Lawyers specialises in personal injury claims across Scotland. The site offers legal services focused on helping individuals claim compensation for injuries sustained through accidents or negligence. Its primary function is to connect potential clients with specialist injury lawyers via a user-friendly platform that emphasizes a No Win No Fee arrangement, ensuring clients pay no upfront costs and retain 100% of their compensation if successful.
personal injury settlements without lawyernegotiating personal injury settlements without a lawyerpersonal injury settlement negotiation letter template