Last Updated: October 23, 2026
Quick Summary
Employer liability insurance work injuries is compulsory cover that protects businesses from financial claims when employees suffer injury, illness, or disease due to workplace negligence. It covers legal costs, compensation payments, and other expenses arising from workplace accidents, ensuring injured workers receive compensation even if their employer faces financial difficulties.
- Employer liability insurance for work injuries is a legal requirement for most UK employers, with minimum cover of £6 million.
- The insurance covers injuries from manual handling, machinery accidents, repetitive strain, slips and falls, and hazardous substance exposure.
- Report workplace accidents immediately to your employer and seek medical attention promptly to preserve your legal rights and strengthen any claim.
- You can claim compensation for medical costs, lost earnings, pain and suffering, rehabilitation, and care costs resulting from your injury.
- Even partial employee negligence doesn't prevent claiming; Scottish law allows compensation if your employer's negligence materially contributed to your injury.
Table of Contents
What Is Employer Liability Insurance for Work Injuries?
Employer liability insurance is a form of cover that protects businesses from the financial consequences of claims made by employees who suffer injury, illness, or disease as a result of their work.
When an employee is injured at work due to negligence or breach of health and safety duties, they may have the right to claim compensation from their employer. Employer liability insurance ensures that the organisation can meet these obligations without facing severe financial hardship.
Understanding employer liability insurance for work injuries is essential for both employers and employees. Employers need to know they're protected, whilst employees should understand what their employer's insurance covers and what it doesn't.
The scope of employer liability insurance for work injuries extends beyond simple slip, trip, or fall incidents. It covers injuries resulting from inadequate training, faulty equipment, poor working conditions, and systemic failures in health and safety procedures.
Pro Tip
Many employers assume their general business insurance covers workplace injuries. It doesn't. Employer liability insurance is a separate and mandatory policy that specifically addresses employee injury claims.
Why Employer Liability Insurance Matters in Scotland
Scotland has its own regulatory framework governing workplace safety and employer responsibilities. The Health and Safety at Work etc.
Employer liability insurance for work injuries serves as a financial safety net when these duties are breached. Without adequate cover, a single serious injury claim could bankrupt a small business.
For employees in Glasgow and across Scotland, knowing that their employer carries proper employer liability insurance for work injuries provides assurance that compensation claims will be met. It removes the risk that an employer's insolvency might prevent a legitimate claim from being paid.
The regulatory environment in Scotland also means that employers face regular inspections and audits by the Health and Safety Executive (HSE). Demonstrating that you hold adequate employer liability insurance for work injuries is part of compliance. Failure to maintain cover can result in fines, prosecution, and reputational damage.
Key Takeaway
In Scotland, employer liability insurance for work injuries isn't optional, it's a legal requirement for almost all employers with employees. The only exceptions are very limited, such as certain family businesses or specific public bodies.
Common Workplace Scenarios Covered by Employer Liability Insurance
Employer liability insurance for work injuries covers many workplace accidents and incidents. Understanding which scenarios are typically covered helps employees and employers alike know when a claim is likely to succeed.
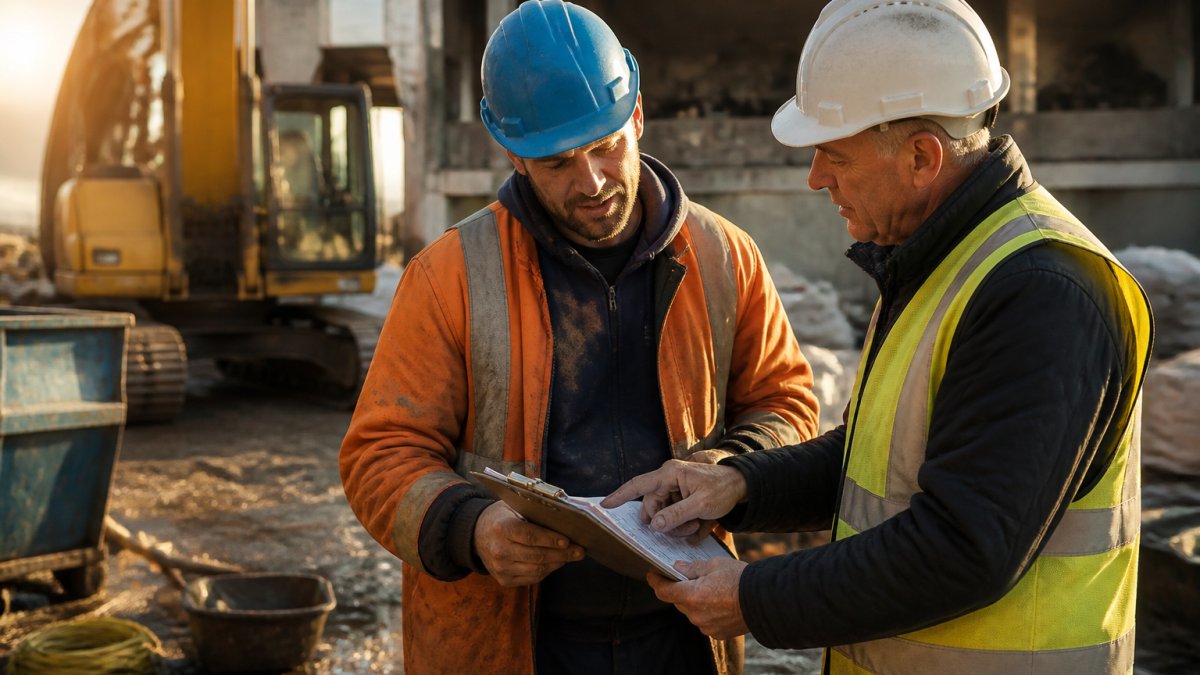 Supervisor and worker reviewing an incident report form at an industrial site to manage employer liability insurance work
Manual handling injuries are among the most common claims.
Machinery and equipment accidents occur when faulty equipment, inadequate guarding, or poor maintenance leads to injury.
Repetitive strain injuries (RSI) and occupational diseases develop gradually through the nature of work performed.
Slips, trips, and falls on company premises are covered when the employer failed to maintain safe conditions. This might include wet floors without warning signs, poor lighting, broken stairs, or cluttered walkways.
Chemical and hazardous substance exposure claims arise when employees suffer injury or illness from inadequate handling, storage, or protection from hazardous materials.
What to Do After an Accident at Work
Immediate action following a workplace accident is crucial for both protecting your health and preserving your legal rights.
Report the incident immediately to your employer or supervisor. Don't wait until the end of your shift or the following day.
Seek medical attention as soon as possible, even if the injury seems minor. Some injuries worsen over time, and medical records created immediately after the accident provide crucial evidence.
Preserve evidence at the scene if it's safe to do so. Take photographs or videos of the location where the accident occurred, the equipment involved, and any hazards that contributed to the injury.
Don't sign anything without reading it carefully. Your employer may ask you to sign an incident form or accident report. Review these documents to ensure they accurately reflect what happened.
Keep a detailed record of your injury and its effects. Write down the date, time, location, and circumstances of the accident.
For guidance on the correct steps to follow after a workplace accident, consult the Scotland Claims Injury Lawyers guide on what to do after an accident at work, which walks through the process in detail.
Watch Out
Many employees delay reporting accidents or fail to seek medical attention promptly because they worry about inconveniencing their employer or fear losing their job. This hesitation can seriously damage your claim. Report immediately and seek medical care, your health and legal rights take priority.
Work Injury Evidence Checklist: What You Need to Gather
Building a strong claim for employer liability insurance work injuries requires comprehensive evidence.
Medical evidence forms the foundation of any claim. Collect GP records, hospital discharge summaries, prescriptions, physiotherapy reports, and any imaging (X-rays, scans).
Witness statements from colleagues who saw the accident carry significant weight. Ask witnesses to provide written accounts of what they observed, including the date, time, and circumstances.
Incident reports and employer records should be obtained from your employer. These documents may include accident reports, incident investigation files, safety meeting minutes, and maintenance records.
Photographic and video evidence of the accident scene, the equipment involved, and any hazards supports your account.
Communications between you and your employer provide a timeline of events. Keep emails, text messages, and letters discussing the accident, your injury, and any accommodation or time off.
Employment records demonstrate your earnings, role, and responsibilities. Payslips, contracts of employment, and performance records help establish the financial impact of your injury.
| Evidence Type |
Why It Matters |
Timeline |
| Medical records |
Proves injury and causation |
Collect within 2 weeks |
| Witness statements |
Corroborates your account |
Gather within 1 month |
| Incident reports |
Employer's own documentation |
Request within 1 month |
| Photographs/video |
Visual proof of hazards |
Obtain immediately |
| Communications |
Shows employer knowledge |
Preserve all messages |
| Employment records |
Quantifies financial loss |
Gather from start |
The Employer Liability Insurance Claim Process Explained
Once you've gathered evidence of your workplace injury, the formal claim process begins.
Step 1: Notify your employer formally that you intend to claim compensation for your workplace injury.
Step 2: The insurer investigates the claim by reviewing evidence, interviewing witnesses, and assessing liability. The insurer's investigator may contact you for a statement.
Step 3: Liability is determined. The insurer will decide whether the employer breached their duty of care and whether this breach caused your injury.
Step 4: Quantum (compensation amount) is assessed. Once liability is established, both parties work to agree on the compensation amount. This includes past and future medical costs, lost earnings, pain and suffering, and any long-term effects of the injury.
Step 5: Settlement negotiation occurs, where your solicitor and the insurer exchange offers and counteroffers. Many claims settle at this stage without proceeding to court.
Step 6: Court proceedings may be necessary if settlement cannot be reached. Your solicitor will prepare evidence, witness statements, and legal arguments for presentation to a judge.
Throughout this process, employer liability insurance for work injuries ensures that funds are available to pay any settlement or judgment.
Accident at Work Compensation in Scotland: What You Can Claim
When you've suffered an injury at work due to your employer's negligence, you may be entitled to compensation.
Past and future medical costs form part of your claim. This includes GP visits, hospital treatment, physiotherapy, prescription medications, and any ongoing or future medical care related to your injury.
Lost earnings cover the wages you've lost whilst unable to work due to your injury.
Pain and suffering (known as general damages) compensates you for the physical pain, emotional distress, and reduced quality of life caused by your injury.
Rehabilitation and retraining costs may be recoverable if your injury prevents you from returning to your previous role.
Aids and adaptations required due to your injury can be claimed. If you need mobility aids, home modifications, specialist equipment, or vehicle adaptations, these costs form part of your compensation.
Travel and care costs incurred as a result of your injury are recoverable.
For detailed information on what compensation is available under Scottish law for workplace injuries, explore the Scotland Claims Injury Lawyers guide on accident at work compensation, which breaks down each category of recoverable loss.
Key Takeaway
The total compensation you receive depends on the severity of your injury, the impact on your earnings and quality of life, and the strength of evidence supporting your claim. More serious, long-term injuries typically result in higher awards than minor, short-term injuries.
Key Benefits of Employer Liability Insurance for Injured Workers
Employer liability insurance for work injuries provides significant benefits to employees who suffer workplace accidents. Understanding these benefits helps injured workers recognise their entitlements and pursue claims with confidence.
Guaranteed payment source ensures that compensation is paid by the insurer rather than relying on the employer's ability to pay.
Legal costs coverage means that the insurer typically covers the cost of defending the claim from the employer's perspective.
Professional claims handling by experienced insurance professionals ensures that claims are processed fairly and efficiently. Insurers have established procedures for investigating claims, assessing damages, and negotiating settlements.
Compensation certainty comes from the fact that employer liability insurance for work injuries is designed specifically to cover these claims.
Access to rehabilitation services may be provided by insurers as part of the claims process.
Faster resolution of claims often occurs because insurers have financial incentives to settle claims efficiently.
Limitations and Exclusions: What Employer Liability Insurance Does Not Cover
Whilst employer liability insurance for work injuries provides broad protection, certain situations and circumstances fall outside the scope of cover. Understanding these limitations helps employees recognise when their claim might face challenges.
Get Started Today →
Wilful misconduct or gross negligence by the employee may exclude cover in some circumstances.
Injuries arising from the employee's own negligence alone (without any employer negligence) are not covered.
Injuries occurring outside the course of employment are excluded.
Pre-existing conditions may be excluded or limited in some policies.
Psychological injuries or stress-related claims can be more difficult to establish and may face higher thresholds for cover.
Injuries caused by intoxication or drug use by the employee may be excluded.
Contractual penalties or fines imposed by regulatory bodies are sometimes excluded from cover, though compensation to the injured employee is typically covered.
How to Assess Your Employer's Liability Coverage
As an employee, understanding your employer's liability coverage gives you confidence that you can claim compensation if injured.
Request proof of insurance from your employer. Most employers display their employer's liability insurance certificate in the workplace.
Check the cover amount shown on the certificate. The minimum legal requirement in the UK is £6 million, though many employers carry higher limits.
Verify the insurer's reputation by checking whether they're authorised by the Financial Conduct Authority (FCA).
Confirm the policy is current by checking the date range shown on the certificate. Employer liability insurance for work injuries must be continuously maintained.
Understand policy exclusions by requesting a copy of the policy document itself.
Ask about historical claims if you're considering employment with a new employer. Employers with a pattern of workplace accidents may indicate inadequate safety systems.
Common Misconceptions About Workplace Injury Claims
Several misconceptions persist about workplace injury claims and employer liability insurance for work injuries. Clarifying these misunderstandings helps injured workers pursue claims with accurate expectations.
"I was partly to blame, so I can't claim" is incorrect. Scottish law allows for apportionment of blame, meaning you can claim even if you were partially at fault. (Source: The Employers' Liability (Compulsory Insurance) Act 1969)
"My employer will sack me if I claim" is a common fear, but it's unfounded.
"Small injuries aren't worth claiming for" underestimates the value of even minor claims.
"The claim will take years to resolve" is often overstated. Whilst complex cases may take time, many workplace injury claims settle within 6-12 months.
"I have to go to court" is not necessarily true. The vast majority of workplace injury claims settle through negotiation without court proceedings.
"My employer's insurance won't pay because they're disputing liability" doesn't mean your claim is lost. Even if the insurer disputes liability initially, this is often a negotiating position.
"I need to claim within a few weeks" misunderstands the limitation period.
Your Rights as an Injured Worker
The right to a safe workplace is your fundamental entitlement.
The right to adequate training and supervision ensures that you're properly equipped to perform your role safely.
The right to compensation when your employer breaches these duties and you're injured as a result is protected by law.
The right to pursue a claim without cost is available through the No Win No Fee arrangement offered by many solicitors, including Scotland Claims Injury Lawyers.
The right to legal representation allows you to instruct a solicitor to handle your claim on your behalf.
The right to protection from victimisation means your employer cannot dismiss you, demote you, or treat you unfairly for making a legitimate workplace injury claim.
The right to access your employer's records relevant to your claim, including incident reports, safety records, and maintenance logs, can be obtained through legal disclosure if necessary.
These rights are protected by Scottish employment law and common law principles of negligence.
Getting Legal Support for Your Workplace Injury Claim
Pursuing a workplace injury claim can be complex, particularly when your employer or their insurer disputes liability or damages.
Why legal representation matters becomes clear when you consider the tactics used by insurers. Experienced insurers employ skilled adjusters and lawyers to defend claims and minimise payouts.
Scotland Claims Injury Lawyers specialises in workplace injury claims and understands the complexities of employer liability insurance for work injuries.
The No Win No Fee model means you pay no legal fees if your claim fails.
Early legal advice helps you avoid common mistakes that damage claims. A solicitor can advise on evidence gathering, communication with your employer, and the proper steps to follow after your accident.
Negotiation expertise allows your solicitor to engage with insurers and employers from a position of strength.
Court representation is available if your claim proceeds to litigation. Your solicitor will prepare evidence, examine witnesses, and present legal arguments to the court on your behalf.
Explore the Scotland Claims Injury Lawyers guide to no win no fee solicitors to understand how this arrangement protects you and maximises your recovery. For immediate guidance on your specific situation, consult the Scotland Claims Injury Lawyers accident at work guide or discover strategies to maximise your compensation.
Pro Tip
Many injured workers delay seeking legal advice because they're unsure whether their claim is worth pursuing. A free initial consultation with a solicitor costs nothing and provides clarity on your position. Most claims are worth pursuing once liability is established, don't assume yours isn't without professional advice.
Key Terms and Definitions
Causation: The legal requirement that the employer's breach of duty must have directly caused or materially contributed to your injury.
Damages: The legal term for compensation awarded to an injured worker.
Employer liability insurance: Insurance cover protecting employers from claims by employees injured due to the employer's negligence.
Liability: Legal responsibility for causing loss or damage.
Negligence: Failure to exercise reasonable care, resulting in loss or damage to another person.
Quantum: The amount of compensation awarded or agreed in settlement of a claim.
Special damages: Compensation for quantifiable financial losses such as medical costs, lost earnings, and travel expenses resulting from injury.
Success fee: The percentage of compensation charged by a solicitor when a claim succeeds under a No Win No Fee arrangement.
Workplace injuries can have profound and lasting effects on your life, your earning capacity, and your wellbeing.
employer liability insurance work injuriesunderstanding employer liability insurance for work injurieswhat to do after an accident at workwork injury evidence checklist